Financial Recap - Week Ending October 2, 2026
Financial Recap - Week Ending October 2, 2026
Financial Recap
Week Ending October 2, 2026
I realized that it is very difficult to keep up daily with financial or economic news, so I decided that on Sunday, when I have plenty of time available, I will kind of recap the whole week for myself just to always stay up to date.
But then I had a thought: why not share it with people who don’t have time to read all the updates and news?
So I will try to do it every week.
Top Topics
The Bond Market Is Still My Number One Worry
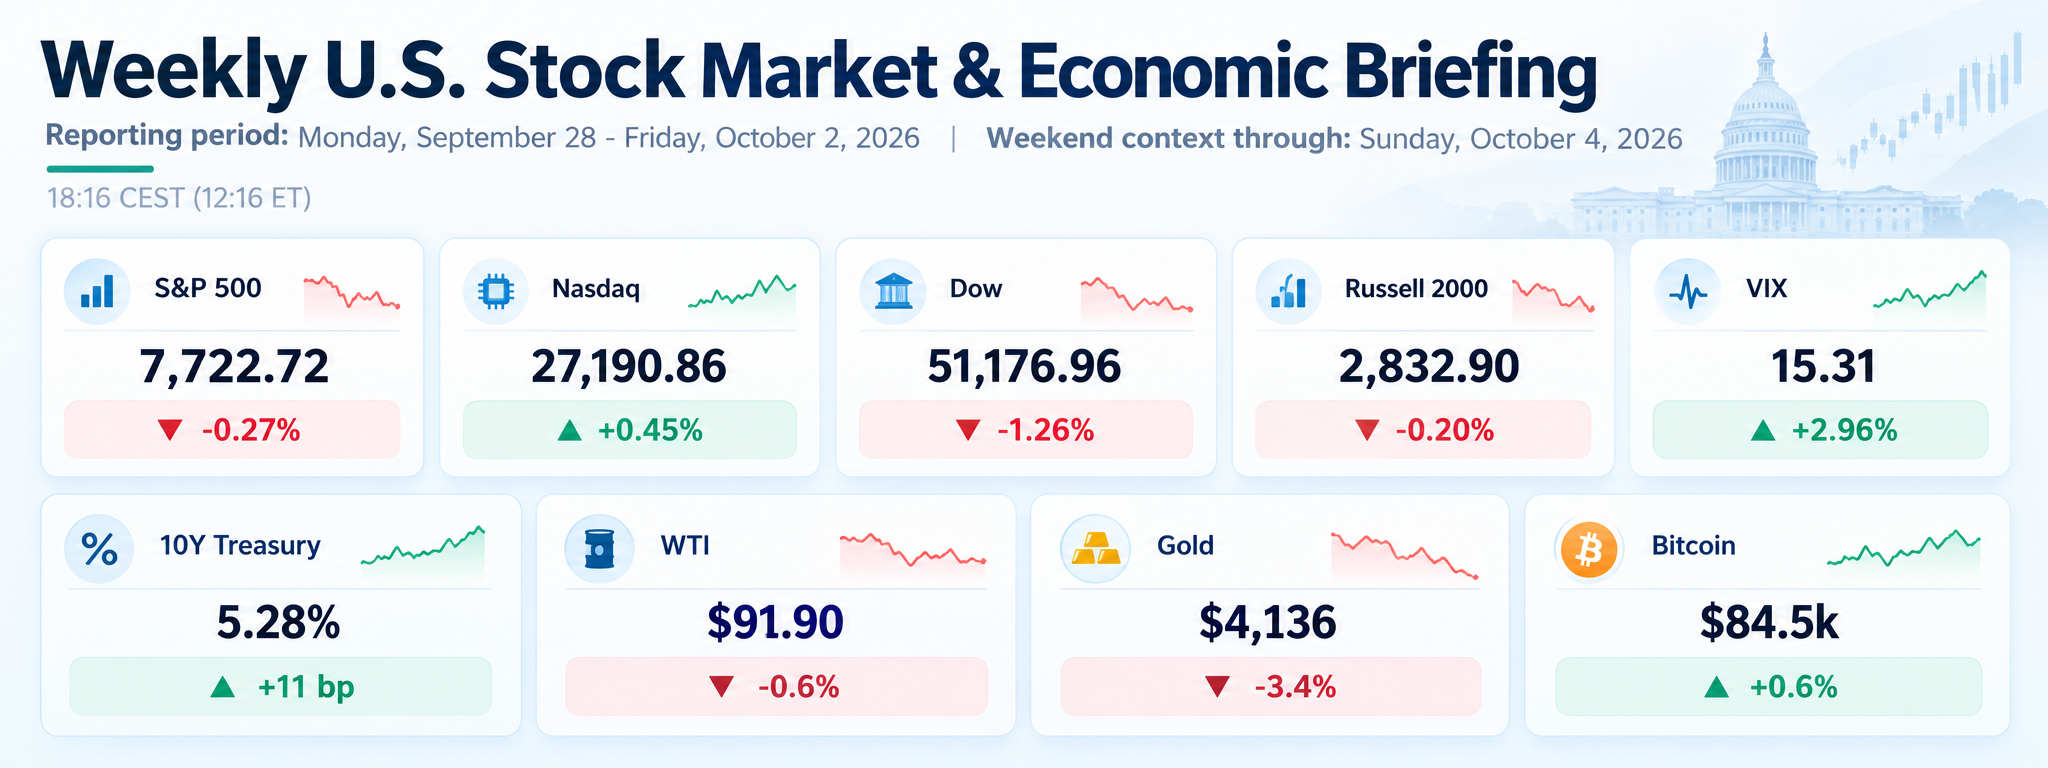
This week’s biggest talking point again was the bond market. The 10-year Treasury yield briefly touched 5.34%, which is the highest level since 2002.
Every time I state the problem, usually right after I follow with my suggested solution. This is one topic where I have no idea how it is going to go.
It is like the U.S. is sitting on a ticking bomb. If bond yields don’t start to drop, refinancing becomes extremely expensive, and the problem is that the government has no other option. It has to refinance maturing debt.
This is my number one worry when it comes to the financial world.
Stock Market
In the stock market, everything seemed pretty normal.
The Dow and S&P 500 had slight drops, while the Nasdaq gained. Tech stocks did fine. Nothing alarming there.
For the week:
Dow Jones: -1.3% S&P 500: -0.3% Nasdaq: +0.5%
Jobs
The jobs report came out, and it was not very positive.
29,000 new jobs were created compared with 90,000 that were expected, and unemployment slightly increased to 4.2%.
Even without this report, right, we can observe these effects personally. Almost no large company is pushing FTE growth. Across companies, I barely see new jobs being created.
I think it is partly AI. Entry-level jobs are not demanded as much since AI can already do some of that work. Instead of two new hires, maybe one hire is enough for the same job.
Economy
Positive news from the economy is that Q2 GDP growth was revised 0.7 percentage points higher, from 1.5% to 2.2% annualized.
Consumer spending also rose in August by 0.9%.
But on the contrary, confidence among consumers started to drop. That could be related to fears around unemployment and the slowdown in hiring.
The revised 2.2% GDP growth is still not large enough for me to assume that we are already seeing AI-related output growth.
U.S.-Iran War and Energy
The U.S.-Iran war is still a big uncertainty. Nothing is really clear, so the energy market is still shaky.
U.S. Market Performance
Top 3 Gainers
Most of the biggest gainers were IT companies this week. I will introduce a couple of interesting ones.
1. Lumentum: +17.81%
It is also data-center-related growth.
Lumentum makes optical and photonic hardware. It can be things such as lasers and transceivers.
Tbh, I don’t really know the engineering behind it in detail, but in simple words, we have this massive amount of compute and data, but that data has to move around from one place to another.
A data center is not one big chip that holds everything. It is thousands of chips.
In order to move data around, basically with Lumentum’s technology, you turn computer electrical signals into light. With light, you can send those signals long distances very fast, and then once they arrive, you turn them back into electrical signals.
Great technology that can be used in many other sectors.
Financials look great on paper, and I don’t see any expected danger in the near future.
One thing I don’t like is the market cap. It is valued at around $98 billion with roughly $3 billion in annual revenue. It is already pricing in several years of growth, so it looks a little bit bloated.
One thing I could not really see at first was whether they had billions of dollars worth of future revenue secured. But Nvidia actually has a multibillion-dollar purchase commitment with Lumentum, plus a $2 billion investment.
Still, they are not the only players. There is competition there.
2. Coherent: +19.33%
Very similar company to Lumentum. I like it more.
Lower market cap
Nvidia is an investor in Coherent. Nvidia invested $2 billion into the company, and there is also a multibillion-dollar purchase commitment, although the exact purchase commitment number has not been disclosed.
If they can deliver and increase their production, I see potential here.
3. Synopsys: +17.31%
Let me introduce the company first.
They sell software for engineers to design, verify, and simulate semiconductors.
With the acquisition of Ansys, they can pretty much go from “silicon to systems”, not just designing the chip but simulating the complete electronic and mechanical system around it.
In short, it is engineering simulation software.
Financially, it is a pretty healthy company. Around 15% revenue growth is expected for FY2027, with revenue expected to be above $11 billion. Its FY2027 non-GAAP operating margin target is around 44%.
They have around $9.9 billion in debt and around $3.6 billion in cash, cash equivalents, and short-term investments.
I personally really don’t like software companies at the moment.
What Synopsys does is extremely difficult. Trust me, designing software that helps you design a chip with millions of transistors is not something where I think tomorrow they are getting outcompeted.
But generally, the trend of creating custom software is picking up. Software becomes less expensive to create, so even very complex simulation software that Synopsys has, I believe at some point customizability will catch up.
Nvidia can just develop in-house software with its own proprietary tools.
3 Losers That Caught My Attention
These were not necessarily the three biggest losers in the entire S&P 500, but they were the three that I found most interesting.
Nike: -6.92%
Oh man, it is so hard to write this.
My childhood iconic brand. Everything I loved was related to Nike.
Yellow Hyperdunks 2013. I bought them and would literally take care of them like my own baby.
Huge fan of Air Force 1s. I think for the last 15 years I have barely worn anything other than Air Force 1s.
But unfortunately, the market became very competitive, and Nike is starting to lose this iconic brand status, especially with the new generation.
Revenue was down 4%, and China continues to be a major problem for the company.
In Europe, we have hot brands like On, Hoka, and Lululemon taking a fair share of Nike’s market.
Really sad to see this.
Definitely would not go long here.
Fair Isaac: -21.36%
FICO is, in simple terms, a credit score provider.
Basically, if you need to get credit, FICO’s scoring models calculate your credit score, and banks can use it to assess you as a borrower.
But something important happened.
The U.S. government expanded the VantageScore mortgage rollout in September.
VantageScore is basically a competitor. They do essentially a similar thing, so if that score becomes more widely adopted, there is a question of what FICO’s future will be.
Financially, it is a very healthy company with pretty high EPS. It prints money, basically.
But scoring revenue is very important for the company, so if that part of the business slows down, there are a lot of unknowns.
McCormick: -7.82%
It is an international spice company.
They are currently doing a merger with Unilever’s food business that could allow them to increase their addressable market significantly and go into different markets.
Very profitable business, but slow growth. Generally, that is characteristic of the sector.
A major investor concern around the deal is how much existing investors get diluted after the merger.
One thing I like is that spices are pretty inelastic.
Whether you buy chicken and $2 vegetables, you can cook them with spices. So I don’t know, if you are really into spices, you might be buying the stock discounted.
I personally don’t use anything other than salt and pepper, so I would stay away for now. I only invest in things that I use
What to Watch This Week
1. FOMC Minutes
What matters: Committee details on the September hike and the path toward October and December.
Positive scenario: Minutes show broad comfort with waiting as labor cools.
Negative scenario: Minutes show broad concern that inflation and energy require another near-term hike.
Markets to watch: 2Y/10Y Treasuries, DXY, Nasdaq, banks.
2. 10Y/30Y Treasury Auctions
What matters: Demand at historically high yields and under heavy sovereign supply.
Positive scenario: Strong bid-to-cover and small tails. Long yields stabilize or fall.
Negative scenario: Weak demand and large tails. 10Y retests or exceeds 5.34%.
Markets to watch: Tech, REITs, utilities, homebuilders, insurers.
3. PepsiCo
What matters: Consumer pricing power, volumes, and commodity and freight cost trends.
Positive scenario: Volumes stabilize and margins hold despite input inflation.
Negative scenario: Elasticity worsens or costs force guidance pressure.
Markets to watch: Staples, retailers, packaging, agricultural inputs.
4. Delta
What matters: Travel demand versus fuel inflation.
Positive scenario: Bookings and pricing remain resilient and fuel impact is manageable.
Negative scenario: Demand softens while elevated fuel prices compress margins.
Markets to watch: Airlines, travel and leisure, refiners.
That’s it for this week.